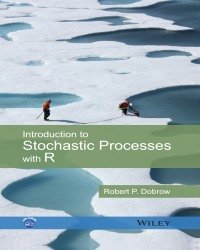
R. Dobrow – Introduction to Stochastic Processes with R (2016)
988 ₽
Автор: R. Dobrow
Название книги: Introduction to Stochastic Processes with R
Формат: PDF
Жанр: Теория случайных процессов
Страницы: 505
Качество: Изначально компьютерное, E-book
An introduction to stochastic processes through the use of R
Introduction to Stochastic Processes with R is an accessible and well-balanced presentation of the theory of stochastic processes, with an emphasis on real-world applications of probability theory in the natural and social sciences. The use of simulation, by means of the popular statistical software R, makes theoretical results come alive with practical, hands-on demonstrations.
Written by a highly-qualified expert in the field, the author presents numerous examples from a wide array of disciplines, which are used to illustrate concepts and highlight computational and theoretical results. Developing readers’ problem-solving skills and mathematical maturity, Introduction to Stochastic Processes with R features:
More than 200 examples and 600 end-of-chapter exercises
A tutorial for getting started with R, and appendices that contain review material in probability and matrix algebra
Discussions of many timely and stimulating topics including Markov chain Monte Carlo, random walk on graphs, card shuffling, Black–Scholes options pricing, applications in biology and genetics, cryptography, martingales, and stochastic calculus
Introductions to mathematics as needed in order to suit readers at many mathematical levels
A companion web site that includes relevant data files as well as all R code and scripts used throughout the book
Introduction to Stochastic Processes with R is an ideal textbook for an introductory course in stochastic processes. The book is aimed at undergraduate and beginning graduate-level students in the science, technology, engineering, and mathematics disciplines. The book is also an excellent reference for applied mathematicians and statisticians who are interested in a review of the topic.
Описание
Introduction to Stochastic Processes with R — это современное учебное пособие, которое знакомит читателей с основными понятиями и методами теории стохастических процессов с активным использованием языка программирования R.
Книга последовательно раскрывает такие темы, как марковские цепи, процессы Пуассона, мартингалы, броуновское движение и диффузионные процессы. Особое внимание уделяется практической реализации всех моделей в R: каждый теоретический результат сопровождается готовым кодом, симуляциями и визуализацией, что помогает глубже понять поведение случайных процессов.
- Студентам математических и экономических специальностей, изучающим стохастические процессы
- Аналитикам данных и специалистам по Data Science, работающим с временными рядами и вероятностным моделированием
- Начинающим исследователям, которым нужна связь теории с реальными вычислительными экспериментами
- Преподавателям, ищущим современный учебник с акцентом на программирование
Только зарегистрированные клиенты, купившие данный товар, могут публиковать отзывы.
Похожие



Другие книги раздела «Математика»
- J. Davis – Methods of Applied Mathematics with a Software Overview (2016)
- F. Catanese – Homological Mirror Symmetry and Tropical Geometry
- A. Petters – An Introduction to Mathematical Finance with Applications (2016)
- C. Chicone – An Invitation to Applied Mathematics (2016)
- G. Simmons – Differential Equations with Applications and Historical Notes (2016)
- V. Petkov – Geometry of the Generalized Geodesic Flow and Inverse Spectral Problems (2017)
- W. Mendenhall – Statistics for Engineering and the Sciences (2017)
- Z. Sanal – Mathematik fur Ingenieure (3 Auflage, 2015, Немецкий язык)
- F. Gazzola – Mathematical Models for Suspension Bridges (2015)
- E. Chin – Problems and Solutions in Mathematical Finance (2 Volumes, 2017)
- R. Aldrovandi – An Introduction to Geometrical Physics (2017)
- D. Luenberger – Linear and Nonlinear Programming (2016)
- R. Larson – Algebra and Trigonometry (2016)
- H. Lombardi – Commutative Algebra (2015)
- Сергей Бобров – Волшебный двурог
- J. Benediktsson – Mathematical Morphology and its Applications to Signal and Image Processing
Все книги раздела «Математика» →
Смежные разделы: Авиация и космонавтика · Астрономия · Геология и Геодезия · Железнодорожное дело · Журналистика · Машиностроение · Нанотехнологии · Научно-популярная литература · Физика · Химия · Экология · Энергетика
Рекомендуем также
- H. Spinelli – Atlas of Aesthetic Eyelid and Periocular Surgery
- Ingrid U. Scott – Diabetes and Ocular Disease (2nd edition)
- Maite Sainz de la Maza – The Sclera (Second edition)
- R. Guthoff – Atlas of Confocal Laser Scanning In-vivo Microscopy in Opthalmology
- S. Dithmar – Fluoreszenzangiographie in der Augenheilkund (Немецкий язык, 2008)
- Alexandrina L. Dumitrescu – Chemicals in Surgical Periodontal Therapy
- Angus C. Cameron – Handbook of Pediatric Dentistry
- Ann Felton – Basic Guide to Oral Health Education and Promotion
Отзывы
Отзывов пока нет.